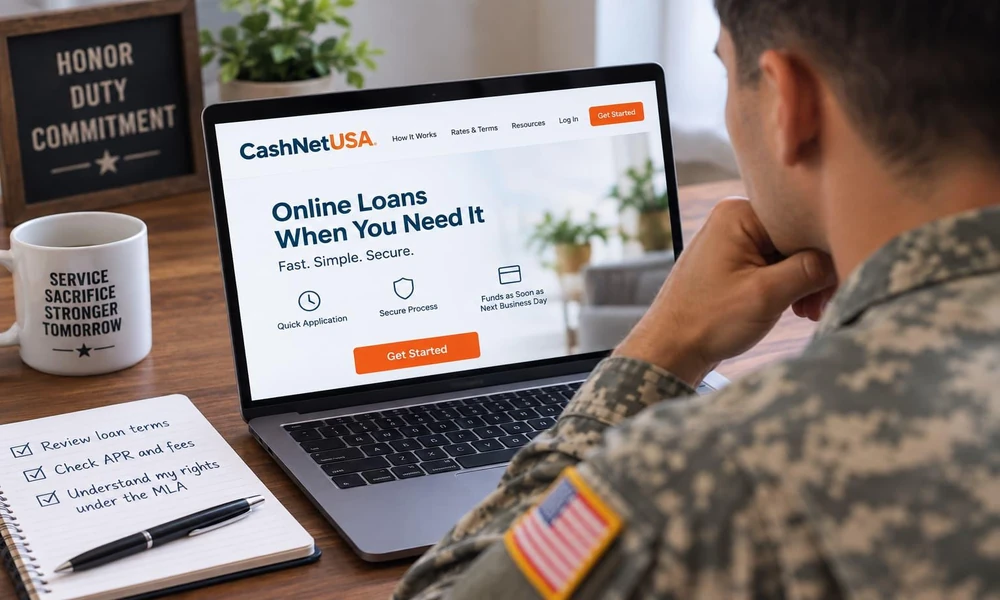
Many online loans are paid back through automatic debits from a checking account. A CashNetUSA automatic withdrawal works the same way, and service members who use it have rights under federal rules, so it helps to know how these payments work.
How Automatic Payments Work
A borrower who signs up for automatic payments gives the lender permission to pull money on set dates. The loan agreement and the payment form show the schedule and the amounts. Under federal rules on electronic transfers, a lender usually cannot make these preset transfers a condition of the loan. A borrower can also take steps to stop future preset payments, and that starts with a call to the bank and the lender.
The CFPB Orders
CashNetUSA is a brand of Enova International. In 2019, the Consumer Financial Protection Bureau (CFPB) issued an order. It found that Enova took money from consumer accounts without permission. In 2023, the CFPB found Enova broke that order and set a civil penalty. Enova agreed to the order but did not admit or deny the findings, and the CFPB ended it in 2025. These orders are background only, so they say nothing about any one borrower’s account.
How the MLA Fits
The Military Lending Act (MLA) protects covered borrowers, mainly active-duty members and eligible family members. Status is judged on the date the loan is signed. The MLA caps the Military Annual Percentage Rate (MAPR) at 36%, and it limits some loan terms. Payment terms are one part of the agreement that an attorney may review.
The Records That Help
Bank statements show each withdrawal, and the payment form shows what the borrower approved. Put those next to the loan agreement and the duty dates, and they give a clear view of the payments.
Active-duty borrowers with questions about CashNetUSA payments can ask for a no-cost consultation with Varnell & Warwick. This article is general information, not legal advice.